Dex International Limited

Author name: bilalkhalid19911@gmail.com

How to Send Money from England to Morocco Safely and Easily
Uncategorized

How to Send Money from England to Morocco Safely and Easily

Sending money from England to Morocco is something many people do to support family, cover personal expenses, pay for important needs, or manage finances in another country. With online money transfer services, the process has become much easier and more convenient than it used to be. Whether you are sending money for the first time or make transfers regularly, it is helpful to understand the basic steps involved. Knowing how the exchange rate, fees, transfer time, and receiving method work can help you make a better choice. If you need to Send Money from England to Morocco, you can usually complete the process online without visiting a bank or carrying cash with you. The sender simply enters the amount they want to transfer, provides the required recipient details, checks the available exchange rate and confirms the payment. Why Do People Send Money from England to Morocco? People send money from England to Morocco for many different reasons. For some, it is a way to support family members with everyday expenses. Others may send money to help with education, household costs, travel, celebrations, or personal purchases. Some people also have property or other financial responsibilities in Morocco and need an easy way to move money between the two countries. Whatever the reason, a simple and reliable transfer process can make managing money across countries much easier. How Does Sending Money to Morocco Work? The process is generally simple. You first choose how much money you want to send in British pounds. The transfer service then shows the exchange rate and the amount the recipient is expected to receive in Moroccan dirhams. You provide the recipient’s information, choose the available payment and receiving options, and review the transfer details before confirming. Once the payment is completed, the money is sent to the recipient through the selected method. The exact process can vary depending on the transfer service, but the main steps are usually very similar. What Currency Will the Recipient Receive? England uses British pounds, while Morocco uses Moroccan dirhams. This means that when you send money from England, your pounds are converted into Moroccan dirhams for the recipient. For example, if you send £500, the recipient will receive the equivalent amount in Moroccan dirhams based on the exchange rate being used for the transfer. Because exchange rates can change, it is a good idea to check the rate before confirming your payment. Why Is the Exchange Rate Important? The exchange rate affects how much money the recipient receives. Even a small difference in the exchange rate can make a noticeable difference when you are sending a larger amount. This is why you should look at the amount the recipient will actually receive rather than focusing only on the transfer fee. Before sending money, check: This gives you a clearer idea of the overall cost of your transfer. How Much Does It Cost to Send Money to Morocco? The cost depends on the transfer service, the amount being sent, and the payment method. Some services may charge a transfer fee, while others may have different charges depending on the transaction. It is important to check the total cost before confirming your transfer. A service with a low transfer fee may not always provide the best overall value if its exchange rate is less favourable. The easiest way to compare is to check how much Moroccan dirhams the recipient will receive after all applicable costs. How Long Does It Take to Send Money to Morocco? Transfer times can vary. Some transfers may arrive quickly, while others can take longer depending on the payment method, receiving method, weekends, holidays, or routine checks. If the recipient needs the money for an important payment, it is better to send it with enough time rather than waiting until the last minute. When making a transfer, check the estimated delivery time before confirming the payment. What Information Do You Need? You will normally need some basic information about the person receiving the money. This may include: Make sure the information is correct before completing the transfer. Incorrect details can cause unnecessary delays. Is It Better to Send Money Online? For many people, online transfers are a convenient option because they can be arranged from a phone or computer. You do not necessarily need to visit a physical location, and you can usually see the exchange rate, fees, and expected amount before confirming the transaction. Online transfers can also make it easier to keep a record of previous payments and check the status of a transfer. The best option depends on your personal needs, but convenience is one of the main reasons people choose online money transfers. Sending Money to Family in Morocco Regular family support is one of the most common reasons people send money from England to Morocco. If you send money regularly, it is useful to choose a transfer method that is easy to use and allows you to clearly see the costs before sending. You should also check the exchange rate each time you make a transfer, as rates can change from one transaction to another. How to Send Money with DEXRemit DEXRemit provides an online option for people who want to send money internationally. The basic process is straightforward. You can enter the amount you want to send, check the available exchange rate and transfer fee, provide the required recipient information, and complete the transfer. For anyone looking for a simple way to manage an England-to-Morocco money transfer, checking the available rate and final amount through DEXRemit’s platform can help you understand the transaction before completing it. Tips for Sending Money Safely A few simple habits can help make your transfer safer. Always double-check the recipient’s details before sending money. Use the official website or application of the service you have chosen, and keep your account information private. You should also avoid sharing passwords or verification codes with anyone. After completing a transfer, keep the confirmation details until you know the recipient has
Uncategorized

How to Get the Best Exchange Rate When Sending GBP to PKR

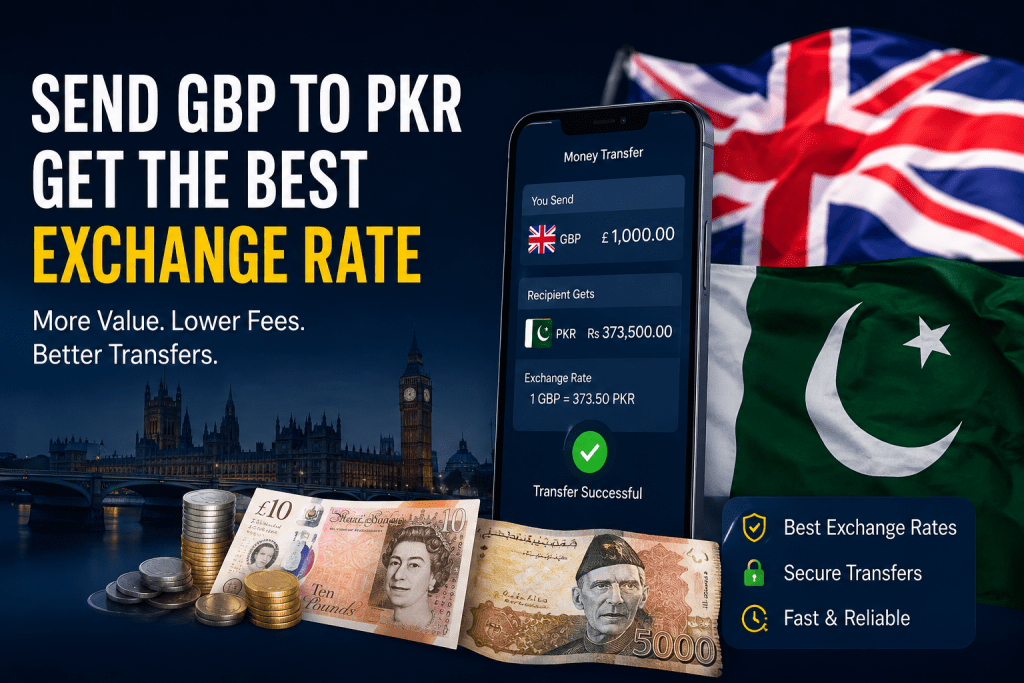
Sending money from the UK to Pakistan is something many people do regularly. Whether you are supporting family, paying for expenses, managing property costs, or simply moving your own money, the exchange rate can make a noticeable difference to the amount received in Pakistan. Even a small change in the rate can affect the final value when you are transferring a larger amount. The good news is that getting a better rate does not always require complicated calculations. By understanding how GBP to PKR exchange rates work, comparing the rate you are being offered, checking the total transfer cost, and choosing the right time and method, you can make more informed decisions. A little attention before confirming a transfer can help you avoid unnecessary costs. If your goal is to Transfer GBP to PKR at best exchange rate, it is important to look beyond the headline exchange rate. The rate is only one part of the overall cost. Transfer fees, hidden margins, receiving charges, and the amount that actually arrives in the recipient’s account can all affect the real value of your transfer. Why the GBP to PKR Exchange Rate Matters The exchange rate determines how many Pakistani rupees you receive for your British pounds. If the rate moves in your favour, the same amount of GBP can produce more PKR. If it moves against you, the recipient may receive less. For example, imagine you want to send £1,000. A difference of just a few Pakistani rupees in the exchange rate can change the final amount by several thousand rupees. This becomes even more noticeable when sending larger amounts or making regular transfers. This is why people should not automatically accept the first exchange rate they see. Taking a few minutes to understand the rate and compare the final amount can make a meaningful difference. How GBP to PKR Exchange Rates Work Currency exchange rates change constantly because currencies are traded in global financial markets. The value of the British pound against the Pakistani rupee can be influenced by economic conditions, interest rates, inflation, political developments, international trade, and market confidence. You may therefore see different GBP to PKR rates at different times of the day or on different days. There is also an important difference between a market exchange rate and the rate offered for a money transfer. A provider may add a margin to the underlying market rate. This means the rate you receive can be different from the rate you see when searching for the current GBP to PKR value. Understanding this difference helps you evaluate whether a transfer offer is genuinely competitive. Don’t Look at the Exchange Rate Alone One of the most common mistakes people make is focusing only on the exchange rate. A transfer showing an attractive rate may still cost more if it comes with a high transfer fee. On the other hand, a service advertising a low or zero fee may offer a less competitive exchange rate. The important figure is the final amount the recipient receives. Suppose one transfer option offers a slightly better exchange rate but charges a noticeable fee. Another offers a slightly lower rate but has a much smaller overall cost. The second option could actually provide more PKR to the recipient. Before sending money, consider these three things together: Looking at the complete transaction rather than one number gives you a much clearer picture of the real cost. Check the Final Amount in Pakistani Rupees The easiest way to compare transfer options is to start with the amount you want the recipient to receive. For example, if you are sending £500, £1,000, or £2,000, check exactly how many Pakistani rupees will arrive after all applicable charges. This approach is more useful than simply asking which provider has the highest advertised rate. The final amount tells you what your money is actually worth after the transfer process. It also makes comparisons easier because you are measuring the same result across different options. If a provider clearly shows the GBP amount, exchange rate, fees, and expected PKR amount before you confirm the transaction, you have a better opportunity to make an informed choice. Why Transfer Fees Can Affect Your Savings Transfer fees may look small, but they can become significant if you send money frequently. Someone sending money once may not be particularly concerned about a small charge. However, a person who transfers money every month could see those charges add up over a year. This is especially important when comparing different services. A lower fee can be useful, but it should always be considered alongside the exchange rate. For example, a service could charge no obvious transfer fee while using a wider exchange-rate margin. Another service could charge a modest fee while providing a stronger exchange rate. The second option may leave the recipient with more money. The best approach is to calculate the complete cost rather than assuming that “zero fee” automatically means the cheapest transfer. When Is the Best Time to Transfer GBP to PKR? There is no guaranteed perfect time to exchange currency. GBP to PKR rates can change because of developments in both the UK and Pakistan, as well as broader international market conditions. Trying to predict every movement is difficult, particularly over short periods. Instead of attempting to find the absolute best possible rate, regular senders can focus on making sensible decisions based on the rate available when they need to transfer. If the transfer is not urgent, you may choose to monitor the rate for a short period. This can help you understand whether the market is moving significantly rather than making a decision based on one moment. However, waiting indefinitely can also work against you. A favourable rate today may not still be available tomorrow. The right balance is to stay informed without trying to perfectly predict the market. Consider the Size of Your Transfer The amount you send can affect how important the exchange rate becomes. For a small

Uncategorized

Modern Architecture of Global Liquidity & Cross-Border Capital Flows

The movement of capital across international borders serves as the lifeblood of the global economy, connecting families, markets, and enterprises across vast geographical divides. As international trade and diaspora populations expand, the demand for efficient, secure, and instantaneous value transfer mechanisms reaches unprecedented heights. Modern financial ecosystems are moving away from sluggish legacy systems toward highly optimized digital architectures. Understanding the foundational mechanics of international currency movement is essential for navigating the complexities of foreign exchange and ensuring that financial resources reach their intended destinations without unnecessary friction. Structural Evolution in International Money Movement For decades, moving money across international boundaries meant navigating a labyrinth of correspondent banking networks, manual verifications, and opaque intermediary fees. Each institution along the transmission chain extracted a portion of the transfer, resulting in reduced payouts and extended delivery windows that often spanned several business days. Contemporary fintech innovations have systematically dismantled these traditional barriers. By integrating decentralized ledger technologies, real-time messaging protocols, and automated clearing houses, modern platforms empower users to execute high-value transactions instantaneously, drastically cutting down overhead costs and administrative delays. Mitigating Currency Volatility and Hidden Costs Foreign exchange fluctuations represent one of the primary variables affecting the net value of an overseas transaction. Market volatility can alter conversion rates rapidly, meaning timing plays a crucial role in maximizing financial outcomes. When individuals seek to Remit Funds from England to Kenya, they encounter dynamic exchange rate margins between the British Pound and the Kenyan Shilling. Navigating these currency corridors successfully requires partnering with platforms that offer transparent mid-market rates and clear, upfront fee structures. Eliminating hidden markups ensures that senders retain absolute control over their capital and recipients receive the full intended value. Regulatory Compliance, AML Protocols, and Security Frameworks Integrity and security remain paramount within the global financial infrastructure. Regulatory authorities worldwide enforce stringent Anti-Money Laundering and Know-Your-Customer mandates to prevent illicit financial activities and protect consumers. Compliance mechanisms operate continuously in the background, utilizing advanced biometric verification, encryption protocols, and artificial intelligence to monitor transactions for anomalies. High-performing platforms seamlessly integrate these rigorous compliance checks into the user journey, ensuring absolute data privacy and legal adherence without compromising transaction velocity or user experience. The Synergy of Digital Wallets and Local Payout Networks The rapid adoption of mobile money and digital wallet infrastructure in developing economies has redefined the final leg of international transfers. Traditional banking penetration in certain regions historically created bottlenecks where recipients had to travel long distances to physical branches. Today, direct integration with mobile wallets bridges this gap, allowing funds to land directly on mobile devices within seconds. This immediate liquidity empowers recipients to settle utility bills, fund education, or manage localized business operations instantly, transforming the utility of cross-border financial remittances. Optimizing Value Through Smart Technological Solutions Maximizing the efficiency of international value transfer involves leveraging platforms designed for speed, affordability, and reliability. Finding a service provider that aligns with individual financial goals prevents unnecessary expenditure on hidden margins. For those seeking a streamlined approach to managing cross-border transactions with minimal friction and maximum security, exploring advanced digital solutions like DexRemit offers a compelling pathway to handle global financial obligations effortlessly. Conclusion Mastering the intricacies of international fund transfers demands a combination of strategic awareness, technological adoption, and careful evaluation of market dynamics. By utilizing modern digital platforms, senders can bypass legacy inefficiencies and ensure their financial assets are handled with maximum security and precision. Understanding these core mechanics ultimately transforms how individuals and enterprises interact with the global financial grid.

Uncategorized

Practical Guide to Secure Money Transfers

Moving financial resources across international borders has become an essential part of modern global connections. Families separated by geography rely heavily on consistent financial flows to support their loved ones, manage household expenses, and fund educational pursuits. The United Kingdom hosts a vibrant community of individuals hailing from East Africa who continuously seek efficient ways to support communities back home. Managing cross-border financial transactions requires a clear understanding of exchange rates, transaction fees, and delivery timeframes. Senders often encounter hidden costs and complicated procedures when attempting to transfer money through traditional banking channels. Finding a streamlined approach ensures that hard-earned money reaches its intended destination securely and without unnecessary deductions. Senders seeking to Remit Funds from England to Somalia often look for methods that combine speed, safety, and transparency. Ensuring that every pound sent translates into maximum value requires careful planning and selection of specialized financial channels tailored specifically for East African corridors. Understanding the Financial Bridge Across Borders The historical and cultural ties linking the United Kingdom with East Africa have fostered deep personal relationships that span thousands of miles. Individuals living in British cities frequently maintain close connections with relatives residing in Horn of Africa regions. This ongoing connection involves regular communication alongside substantial financial assistance designed to uplift households, construct properties, and invest in local enterprises. Recognizing how these financial corridors operate helps senders make informed choices regarding their international transfers, avoiding common pitfalls associated with outdated financial systems. Financial participation across international boundaries relies heavily on accessibility and speed. When people work hard to earn a living abroad, they want the absolute assurance that their contributions arrive safely and promptly. Traditional banking networks often impose rigid restrictions, high intermediary fees, and protracted processing windows that frustrate both the sender and the recipient. Modern financial technology addresses these gaps by creating direct pathways that eliminate unnecessary middle layers and reduce overhead expenses, ensuring higher efficiency for everyone involved. Key Factors Influencing Transfer Speeds and Exchange Rates Exchange rate fluctuations significantly impact the final amount received by beneficiaries overseas. Currency markets shift constantly based on macroeconomic indicators, political stability, and global trade dynamics. Senders must evaluate how conversion rates apply to their specific transfers, as minor variances can alter the total funds delivered. Additionally, operational hours, banking holidays, and recipient bank infrastructure dictate whether a transfer clears within minutes or stretches across multiple business days. Operational transparency plays a critical role in mitigating unexpected costs. Many legacy institutions obscure their true pricing behind favorable exchange rates laden with hidden margins. Senders benefit greatly from utilizing channels that provide upfront cost breakdowns, clear fee structures, and real-time rate updates. This level of clarity empowers individuals to choose the exact moment to initiate their transfers for maximum financial return. Navigating Regulatory Compliance and Security Standards Financial regulations exist to protect consumers and prevent illicit activities such as money laundering or fraud. Authorized money service businesses operate under strict legal frameworks mandated by financial conduct authorities in the United Kingdom. Compliance measures require identity verification for both senders and beneficiaries, ensuring that every transaction remains traceable and lawful. Adhering to these rigorous protocols protects users against security breaches and builds enduring trust within immigrant communities. Security in digital transactions extends beyond legal compliance. Advanced encryption technologies, secure server architecture, and multi-factor authentication safeguard user data from unauthorized access. Senders should verify that their chosen provider implements comprehensive data protection policies. Knowing that personal and financial information remains confidential allows users to complete their transactions with complete peace of mind. Empowering Families Through Reliable Financial Support Financial remittances serve as a vital lifeline for numerous households, funding essential necessities such as healthcare, nutrition, and schooling. Regular monetary support contributes to regional economic stability by injecting capital directly into local markets. When transaction channels function smoothly, families experience reduced stress and greater predictability in managing their day-to-day budgets. This steady inflow of resources plays a transformative role in improving living standards across recipient communities. Beyond immediate household needs, transferred funds frequently finance small business ventures, agricultural projects, and infrastructural improvements. These investments create local employment opportunities and foster long-term economic independence. Senders take immense pride in knowing their financial contributions yield lasting developmental impacts for future generations in East Africa. Overcoming Traditional Banking Hurdles for International Senders Conventional high street banks often treat international money transfers as secondary services, resulting in exorbitant charges and poor customer support. Senders frequently experience delayed clearances and opaque fee structures that obscure the true cost of their transactions. Transitioning away from legacy institutions allows users to experience transparent pricing models, dedicated customer assistance, and digital platforms designed specifically for cross-border payments. Furthermore, traditional banks often lack specialized payout networks in developing regions, leading to cumbersome intermediary transfers that cause further delays. Specialized remittance providers focus entirely on optimizing specific country corridors, ensuring direct delivery routes and faster availability of cash or bank deposits for the recipient. Advanced Digital Solutions for Cross-Border Transactions Dedicated financial platforms provide specialized infrastructure focused exclusively on optimizing remittance flows from Europe to various global destinations. These systems utilize advanced encryption protocols and streamlined mobile applications to ensure users can initiate transactions effortlessly from any location. By maintaining strong relationships with payout networks and utilizing robust compliance frameworks, these platforms deliver fast, secure, and cost-effective services. Users benefit from competitive conversion rates, minimal service charges, and twenty-four-hour customer support that addresses any inquiry promptly, ensuring complete peace of mind throughout the entire transfer lifecycle. For those seeking a reliable digital experience, DexRemit offers optimized solutions tailored for international senders. Conclusion Financial remittances represent a powerful mechanism for maintaining familial bonds and driving economic growth across international borders. Understanding the mechanics of currency exchange, regulatory compliance, and transfer speeds enables senders to maximize the value of every single transaction.

Uncategorized

How Overseas Pakistanis Send Funds Home Fast

In many historical scenarios, conventional bank transfers required multiple business days to process funds across borders. Differences in working hours, correspondent banking networks, manual clearing cycles, and weekend schedules frequently delayed capital delivery, leaving families waiting in uncertain conditions during crucial financial moments. When urgent family commitments arise, choosing a reliable Same day money transfer UK to Pakistan channel becomes the primary requirement for senders who cannot afford multi-day clearing delays. Operating through modern electronic settlement frameworks allows funds to move across international channels swiftly, ensuring that receivers gain immediate access to their funds without unexpected holding periods. To understand how same-day settlement operates, it helps to examine how funds move from a British banking account into a Pakistani bank account or mobile wallet. Payment gateways leverage local payout liquidity and instant clearing protocols such as Pakistan’s national instant payment infrastructure. By maintaining pre-funded clearing reserves in local currency, modern remittance systems convert British Pounds into Pakistani Rupees almost instantly, removing the friction associated with traditional correspondent clearing chains. Primary Drivers Demanding Rapid Cross-Border Capital Movement Timing plays a central role in how overseas remittances impact households in Pakistan. Family emergencies, such as unexpected medical treatments or urgent hospital bills, demand immediate liquid funds. Delayed bank clearings in these situations can create severe strain, making immediate fund access an absolute necessity for families relying on support from abroad. Beyond emergency health requirements, time-sensitive financial obligations like utility bills, school tuition deadlines, monthly rental payments, and property deal settlements depend on predictable clearing schedules. Senders want complete assurance that their hard-earned money will land in the target account on the exact day it leaves their UK bank balance. Small business operations and freelance contractors operating across the UK and Pakistan also benefit immensely from accelerated capital settlement. Timely payments for goods, services, and operational expenses keep small supply chains running smoothly, fostering economic growth and strengthening financial stability for families relying on regular incoming transfers. Key Variables That Influence Transaction Speeds and Exchange Rates Achieving fast turnaround times depends on several technical and procedural factors. First, the payment method chosen by the sender heavily dictates velocity. Debit card payments and instant online banking authorizations process almost instantly, whereas manual bank transfers or cash deposits at physical counters might introduce processing buffers. Second, foreign exchange rate calculations and fee transparency dictate the final rupee payout amount received by family members. Currency markets shift constantly throughout trading hours, meaning live rates ensure senders get maximum value for every pound transferred. Platforms with transparent, real-time rate displays protect customers from hidden spread margins. Finally, payout mechanisms in Pakistan affect how quickly recipients can spend or withdraw their money. Payouts sent directly to commercial bank accounts, IBAN numbers, or registered mobile wallet accounts settle far faster than physical cash pickup arrangements, which rely on branch operating hours and physical location availability. Regulatory Safeguards and Compliance Checks Behind Swift Remittances Financial security and speed must operate hand in hand when moving funds across international borders. Financial institutions operating in the United Kingdom are regulated under strict supervisory frameworks established by financial conduct regulatory bodies and revenue departments. These rules enforce robust Anti-Money Laundering and Know Your Customer standards to keep funds completely safe. Automated verification tools allow modern platforms to execute real-time identity checks, sanctions screening, and anti-fraud assessments within seconds. Instead of causing multi-day delays, automated compliance tools verify user credentials during the application process, preserving speed while maintaining institutional-grade security. For customers, completing full account verification beforehand ensures smooth, uninterrupted transactions. Providing clear proof of identity, such as a valid passport or driving license, along with verified proof of address, prevents unexpected account holds and allows high-value transfers to pass through automated clearing channels without manual intervention. How Modern Payment Corridors Eliminate Intermediary Delays Traditional international wire transfers passed through multiple intermediary banks, each applying handling fees, manual compliance checks, and local batching routines. This multi-tiered structure led to high costs, unpredictable delivery times, and hidden conversion markups. Direct remittance corridors bypass unnecessary middleman layers. By connecting UK originators straight to local clearing houses and payment switch networks in Pakistan, money transfers move directly from sender to recipient. Real-time API integrations communicate account validations instantly, reducing errors caused by mistyped account details or incorrect bank branch codes. Furthermore, the expansion of 24/7 digital banking services in Pakistan means funds arrive in receiver accounts even on weekends or public holidays. This continuous operation gives senders peace of mind, knowing that money sent on a Saturday afternoon will reach its destination without waiting for Monday morning bank openings. Practical Steps to Guarantee Uninterrupted Clearing Times Senders can adopt a few straightforward habits to guarantee consistent same-day completion for every transaction. Accuracy during recipient data entry ranks as the most critical factor. Always double-check the recipient’s full name, bank name, account number, and 24-character IBAN or registered mobile wallet number before confirming the transfer. Timing your transfer within peak processing windows can also streamline delivery. While digital platforms operate around the clock, initiating transfers during morning hours in the UK aligns well with business hours in Pakistan, allowing local banking systems to finalize domestic settlements effortlessly. Maintaining updated profile details on your remittance app prevents sudden compliance pauses. If your residential address, phone number, or ID document expires, update your information proactively so your account remains fully active for urgent money transfers whenever you need them. Why DexRemit Is the Smart Choice for Fast and Secure UK-to-Pakistan Remittances For UK residents seeking a dependable, transparent, and ultra-fast pathway to send money home, DexRemit offers a tailored digital remittance experience. Operating as an established financial services provider incorporated in the United Kingdom since 2008, DexRemit brings deep industry expertise, strict regulatory compliance standards, and dedicated service to the Pakistani diaspora community. DexRemit eliminates traditional transfer headaches by providing competitive exchange rates, low fees, and direct connections to major commercial banks and mobile wallet platforms across Pakistan. Whether sending funds to a bank account in Lahore, a mobile

Uncategorized

Exploring Modern Solutions for Cross-Border Capital Flow

Moving financial assets across international borders has evolved dramatically over past decades, transitioning from slow bureaucratic banking channels to lightning-fast digital solutions. Families separated by geography often rely heavily on regular funds sent back home or vice versa to sustain households, fund education, or manage investments. Understanding the underlying mechanisms of global currency exchange ensures that senders maximize their value while avoiding hidden costs or unnecessary delays. The corridor connecting South Asia and Europe sees substantial financial activity due to a thriving diaspora living abroad. Workers and professionals continuously seek reliable avenues that combine safety, speed, and affordability. Traditional banking institutions frequently impose burdensome charges and prolonged clearance times, prompting users to explore innovative fintech alternatives designed to streamline the entire experience from initiation to final payout. Ensuring continuous assistance during international transactions remains a cornerstone of reliable financial services, especially when dealing with differing time zones and regulatory frameworks. Having access to 24/7 support for Pakistan to UK money transfer guarantees that any unexpected verification hurdles, technical glitches, or delivery queries receive immediate professional attention regardless of the hour. Users benefit immensely from knowing expert assistance stands ready to resolve bottlenecks before they escalate into major disruptions. Understanding Regulatory Compliance in International Remittances Regulatory frameworks govern every aspect of global currency movement to prevent illicit activities and protect consumer interests. Financial authorities require rigorous identity verification protocols, commonly known as Know Your Customer standards, alongside stringent Anti Money Laundering checks. When sending funds across borders, institutions must vet both the sender and the recipient to ensure complete transparency. This layered scrutiny safeguards the global financial ecosystem from fraudulent actors while establishing a secure legal baseline for legitimate transactions. Navigating these requirements demands careful attention to documentation, ensuring that proof of income and identification match official records seamlessly. Evaluating Exchange Rates and Hidden Markup Costs Exchange rates dictate the actual value received by the beneficiary after conversion from one currency to another. Many conventional wire services advertise low transfer fees while concealing high profit margins inside unfavorable currency exchange rates. Discerning senders look past promotional slogans to identify the true mid market rate, which reflects the real wholesale price of currencies traded globally. By choosing platforms that offer absolute transparency regarding conversion markups, individuals can retain a significantly larger portion of their hard earned money. Calculating the total cost involves multiplying the amount sent by the quoted rate and subtracting any fixed service charges. Speed Versus Security in Digital Fund Transfers Balancing rapid delivery speeds with robust protection mechanisms is a primary challenge for modern fintech engineers. Users naturally prefer transactions that settle within minutes rather than days, yet bypassing security checks introduces vulnerability. Assessing Blockchain Encryption Standards Advanced cryptographic protocols provide an immutable ledger system that records every stage of a transaction transparently. This distributed architecture eliminates single points of failure, making unauthorized alteration virtually impossible. Mitigating Fraud Risks in Cross-Border Channels Continuous monitoring algorithms analyze behavioral patterns to detect anomalous activities instantly. Multi factor authentication requirements further reinforce user accounts against potential cyber threats, ensuring capital remains protected throughout transit. The Role of Mobile Wallets and Direct Bank Deposits The disbursement phase of international fund transfers determines how quickly recipients can access their money. Direct bank deposits routed through automated clearing houses offer traditional reliability, though they can experience processing delays over weekends. Conversely, integration with digital mobile wallets enables instantaneous crediting directly to smartphone applications. Recipients can then utilize these funds for immediate retail purchases, utility bill payments, or cash withdrawals at local ATM networks. Offering diverse payout modalities ensures that recipients choose the most convenient method available in their locality. Managing Multi Currency Accounts for Optimal Savings Holding multiple currencies within a single digital dashboard empowers users to capitalize on favorable market fluctuations. Instead of converting funds immediately upon deposit, account holders can store foreign currencies until exchange rates reach an advantageous threshold. This strategic approach minimizes losses associated with volatile market shifts and provides greater flexibility for frequent travelers or remote workers receiving payments from overseas clients. Budgeting becomes simpler when funds can be allocated directly into designated currency pockets without incurring repeated conversion fees. Streamlining Financial Communication for Expatriate Families Maintaining financial harmony across distant households requires clear, real time communication channels between senders and recipients. Modern digital portals feature instant notification systems that update both parties via push notifications or SMS messages at every milestone of the transaction lifecycle. Knowing precisely when funds leave the source account, clear customs clearance, and arrive at the destination eliminates guesswork and anxiety. Furthermore, integrated messaging tools allow users to attach specific notes or purpose declarations to individual transfers, ensuring complete clarity for accounting and family budgeting purposes. Advanced Technological Solutions for Instant Global Settlements Leveraging decentralized liquidity pools and next generation blockchain infrastructure transforms how international payments are executed. By removing legacy correspondent banking intermediaries, transactions bypass traditional clearance delays and costly overhead charges. Users benefit from decentralized networks that facilitate peer to peer settlement with complete transparency and minimal friction. Advanced cryptographic validation ensures that every ledger entry remains immutable, protecting users from unexpected chargebacks or processing errors while providing near instantaneous value availability across international divides. Conclusion Navigating the complexities of international finance requires a comprehensive understanding of regulatory standards, exchange rate mechanics, and digital security measures. By prioritizing transparency and efficiency, individuals can protect their hard earned capital while ensuring swift delivery to loved ones abroad. The ongoing evolution of financial technology continues to bridge geographical gaps, making international capital movement simpler and more accessible than ever before. As global economic connectivity deepens, understanding the broader implications of financial migration and monetary flow becomes essential for expatriate communities. Historical ties and trade agreements heavily influence how capital moves across borders, shaping the broader landscape of remittance practices worldwide. Embracing these advanced digital tools empowers users to take full control of their cross border financial obligations with confidence and precision. Ultimately, choosing the right digital partner ensures that every financial commitment is fulfilled

Uncategorized

Decoding the True Cost of Cross Border Capital: Routing GBP to PKR Efficiently

The continuous flow of capital across international borders often feels like navigating a complex labyrinth designed to extract value at every possible turn. Expatriates and professionals working across the United Kingdom frequently face the silent attrition of their hard-earned capital when sending financial support or investment funds back home. The core frustration does not stem from the act of transferring wealth itself but from the opaque network of intermediary banking institutions that quietly degrade the principal amount before it ever reaches the local jurisdiction. Senders expect a simple transaction from point A to point B, yet the reality involves a convoluted web of correspondent banking nodes that prioritize institutional profit over user efficiency. To understand why international capital routing is so inefficient, one must look at the underlying architecture of global finance. Traditional banking systems do not physically move liquidity across oceans in real time. Instead, they rely on a messaging infrastructure where financial institutions instruct each other to debit and credit respective accounts. When a sender initiates a transfer from a British high street bank, the institution must locate a partner bank in the destination country. If a direct relationship does not exist, the capital is routed through a third-party intermediary. Each node in this chain demands a toll for its participation, resulting in lifting fees, processing charges, and delayed clearance times that severely impact the end recipient. The most significant financial leakage occurs precisely when users attempt to bypass upfront costs without understanding the mechanics of currency valuation. Individuals constantly search for ways to Wire money from UK to Pakistan without high fees, only to fall into the trap of zero-commission marketing. Retail financial providers frequently advertise transfers with no upfront processing cost while silently embedding their profit margins directly into the exchange rate. They purchase the foreign currency at the wholesale interbank rate and sell it to the retail consumer at a significantly weakened valuation. This hidden spread means the sender pays a steep premium implicitly, losing a substantial percentage of the total capital value right at the point of origin. The Hidden Arithmetic of Exchange Rate Markups The true cost of any international transaction is rarely found on the receipt provided by the originating institution. The global currency market operates on a wholesale valuation known as the mid-market rate, which represents the true equilibrium between the supply and demand of two currencies. Institutional traders and massive liquidity providers access this rate directly. However, retail consumers and small business owners are deliberately excluded from this baseline valuation. When an individual initiates a transfer, the facilitating institution applies a retail markup, effectively creating a completely different exchange environment designed to capture a percentage of the total volume. This deliberate manipulation of the exchange rate is where the majority of capital is lost during the routing process. If the interbank rate dictates that one British Pound equals a specific number of Pakistani Rupees, the retail provider might offer a rate that is two to three percent lower. On a substantial transfer intended for property investment or critical supply chain payments, this mathematical discrepancy translates into a massive loss of purchasing power for the receiving party. The sender assumes they have secured a favorable deal because the advertised transfer fee was zero, completely unaware that the institution has extracted its revenue through the artificially suppressed exchange rate. This markup is entirely unregulated and fluctuates based on the profit targets of the specific institution facilitating the transaction. Financial providers know that the average consumer rarely monitors real-time interbank charts, allowing them to widen the spread during periods of high market volatility. When the market experiences turbulence, these institutions protect their own margins by offering even worse rates to the consumer. The lack of transparency in this arithmetic ensures that the sender carries the entirety of the financial risk while the facilitating network guarantees its own profit regardless of market conditions. Structural Bottlenecks in Traditional SWIFT Routing The infrastructure governing the majority of international capital movement was conceptualized decades ago and remains fundamentally unsuited for the demands of modern global commerce. The standard method for institutional transfers relies on a messaging protocol that merely transmits settlement instructions between disconnected financial ledgers. Because there is no centralized clearing house for global transactions, banks must maintain pre-funded accounts with each other, known as Nostro and Vostro accounts, to facilitate immediate liquidity. Maintaining these dormant pools of capital is incredibly expensive for financial institutions, and they pass those operational costs directly down to the consumer. When an originating bank in London does not hold a direct Nostro account with a receiving bank in Karachi or Lahore, the system breaks down into a slow, fragmented process. The originating institution must transmit the capital to a larger intermediary bank that holds relationships with both parties. This intermediary steps into the transaction flow, holding the funds for compliance checks and manual reconciliation before passing them along to the final destination. This multi-hop routing causes severe delays, transforming what should be an instantaneous digital update into a multi-day waiting period that disrupts cash flow for the intended recipient. The cost of unplanned downtime during these prolonged transit periods cannot be overstated. When capital is locked in a pending status across multiple banking jurisdictions, the sender loses all visibility and control over their assets. If a discrepancy arises regarding the beneficiary account details or the formatting of the routing numbers, the funds do not simply bounce back. They become trapped in a suspense account at an intermediary node, requiring manual intervention, investigative fees, and weeks of bureaucratic communication to retrieve. The structural rigidity of this legacy system directly punishes the consumer for the technical limitations of the banks themselves. Navigating Currency Volatility During Transit Currency valuation is a dynamic, ever-shifting metric influenced by macroeconomic policies, inflation data, and geopolitical events. The exchange rate between the British Pound and the Pakistani Rupee rarely remains static for more than a few minutes. This inherent volatility introduces a massive element of risk

Uncategorized

The Modern Guide to Cross-Border Money Transfers

The process of relocating financial assets across international borders requires rigorous planning and a thorough understanding of global banking architecture. Individuals and corporate entities frequently engage in these transcontinental transactions for a multitude of diverse purposes, ranging from crucial family financial support and real estate acquisitions to complex corporate investments and trade settlements. Operating within the robust financial ecosystem of the United Kingdom demands strict adherence to comprehensive regulatory standards while simultaneously navigating the continuous volatility of foreign exchange markets. A highly successful cross border transaction depends on evaluating various logistical factors, understanding the underlying banking infrastructure, and choosing modern methods that prioritize both impenetrable security and rapid efficiency. The landscape of financial mobility has evolved significantly over the past decade, shifting away from monopolistic traditional banking models toward highly specialized financial technology solutions that offer unprecedented transparency. Consumers are no longer restricted to opaque banking practices; they now possess the tools to execute high volume transactions with granular control and total visibility. This comprehensive guide details the critical components necessary for optimizing outbound capital movements, ensuring that senders can protect their principal investments while facilitating seamless international deliveries. Decoding the Core Mechanisms of International Currency Exchanges Understanding the underlying architecture of global finance is absolutely essential for anyone initiating transcontinental transactions. Traditional banking institutions rely heavily on legacy infrastructure to facilitate global communication and capital clearance. This conventional system operates strictly as a messaging protocol rather than a centralized clearing house, meaning the actual funds must pass sequentially through an intricate network of correspondent banks before finally reaching the designated beneficiary. Each intermediary institution involved in this complex chain processes the transaction through manual or semi automated verification systems, which inevitably introduces substantial delays and triggers cumulative administrative fees at every checkpoint. This structural complexity explicitly explains why conventional wire transfers often result in unexpected and frustrating deductions from the initial principal amount. Modern financial frameworks attempt to completely bypass this archaic network by establishing localized pre funded liquidity pools in both the originating and destination countries. By holding massive institutional reserves in both jurisdictions, specialized financial providers can simulate a cross border transfer without physically moving capital across international lines. When a sender deposits funds in the United Kingdom, the platform simply releases the equivalent amount from its existing reserves in the destination country. This structural innovation entirely eliminates the reliance on intermediary banking networks, thereby preserving the exact value of the initial capital and dramatically accelerating the final settlement process. Strict Regulatory Frameworks Governing UK Outbound Remittances Any outbound capital movement originating from the United Kingdom is strictly subject to rigorous oversight by comprehensive financial regulatory bodies, primarily the Financial Conduct Authority. These governing entities mandate absolute compliance with Anti Money Laundering protocols and extensive Counter Terrorism Financing regulations to maintain the integrity of the global economy. Financial institutions are legally obligated to perform exhaustive Know Your Customer verifications before authorizing any transaction. This intensive process requires users to submit government issued identification documents, verify their residential address, and occasionally provide legally binding proof regarding the exact source of their funds. While these mandatory security measures might initially appear overly bureaucratic, they remain fundamentally necessary for preventing illicit financial activities. Furthermore, the regulatory landscape strictly dictates how licensed financial providers must safeguard consumer funds during transit. Regulated entities are compelled to employ a strict practice known as safeguarding, which involves storing client money in specially designated segregated accounts that are completely isolated from the company’s own operational capital. In the highly unlikely event of institutional insolvency or operational failure, this absolute legal separation guarantees that the sender’s capital remains completely protected and fully recoverable. Analyzing Exchange Rate Fluctuations and Their Financial Impact The global foreign exchange market is a highly volatile ecosystem, perpetually influenced by shifting macroeconomic indicators, unpredictable geopolitical events, and precise central bank monetary policies. Even a fractional decimal shift in currency valuation can significantly alter the final capital received by the beneficiary. Exploring the Core Interbank Rate Dynamics The interbank exchange rate represents the fundamental baseline valuation at which major global financial institutions trade wholesale currencies with one another. This foundational figure serves as the purest indicator of a currency pair’s true market value and fluctuates continuously throughout the active trading session. Financial institutions rigorously monitor these baseline metrics to calculate their own operational risk before offering consumer facing rates. Securing a valuation that closely mirrors this interbank benchmark is the most crucial element in preserving capital integrity during cross border operations. Recognizing and Calculating Hidden Markup Practices The vast majority of retail banking services and conventional transfer providers deliberately avoid offering the raw mid market rate to their retail clients. Instead, they apply a highly variable margin or markup directly to the baseline valuation. This strategically hidden percentage acts as an extremely lucrative secondary revenue stream for the institution, routinely costing the sender significantly more than any explicitly advertised flat transaction fee. Accurately identifying and calculating this specific margin empowers consumers to maximize the true efficiency of their financial asset relocation. Strategic Timing for Optimal Currency Conversion Global currency markets respond instantaneously to national economic data releases, inflation reports, and strategic alterations in domestic interest rates. Astute individuals carefully monitor these detailed financial calendars to identify mathematically advantageous windows for executing their transactions. For individuals looking to move money from England to Jordon, timing plays a pivotal role in maximizing the purchasing power of the transferred funds. The continuous fluctuations in the valuation of the British Pound relative to Middle Eastern currencies routinely create brief highly favorable periods where the exchange yields significantly higher returns. Advanced financial platforms provide sophisticated market tools, including forward contracts and precision limit orders, to help users capitalize on these unpredictable market movements. A precision limit order allows a user to specify an exact target exchange rate, programming the system to automatically execute the transaction only when the global market reaches that specific mathematical threshold. This automated precision removes the emotional stress of constant manual market monitoring

Uncategorized

What Makes UK to India Remittances So Important?

The flow of capital between the United Kingdom and India represents one of the most active and significant financial corridors globally. This relationship is built upon deep historical ties, a robust diaspora, and a growing interconnectedness between the technological and educational sectors of both nations. When individuals or businesses move money across these borders, they are participating in a complex system that involves currency markets, regulatory oversight, and advanced digital infrastructure. Understanding how this system functions provides the necessary insight for making informed financial decisions rather than relying on outdated banking practices. At the core of this exchange lies the conversion of British Pounds (GBP) into Indian Rupees (INR). This process is rarely a simple one-to-one transfer of value. Instead, it involves multiple layers of verification and processing. The currency market operates continuously, and the value of these currencies fluctuates based on global economic indicators, central bank policies, and trade balances. Those involved in moving capital often find that the timing of a transaction can impact the total amount received on the other side. By observing market trends, individuals can better time their transactions to align with favorable exchange rates. Regulatory Frameworks and Compliance Requirements Every international financial transaction is subject to a strict set of regulations designed to ensure transparency and prevent illicit activities. In the United Kingdom, financial institutions are governed by the Financial Conduct Authority (FCA), which mandates that any entity handling money transfers must adhere to rigorous anti-money laundering (AML) and know-your-customer (KYC) protocols. These rules are not merely bureaucratic hurdles but essential safeguards that protect both the sender and the recipient. When transferring money, one must be prepared to provide documentation, such as proof of identity and the source of funds. On the receiving side, India operates under the regulatory purview of the Reserve Bank of India (RBI) and the Foreign Exchange Management Act (FEMA). FEMA is particularly important as it dictates how foreign currency enters the country and ensures that such inflows are legitimate and tracked. Banks and authorized money transfer operators in India must comply with these directives. This dual-layer of regulation, involving both the UK and Indian authorities, ensures that the financial ecosystem remains stable. Understanding these requirements helps users prepare the necessary documentation in advance, which significantly reduces the likelihood of transaction delays. The Evolution of Exchange Rates and Hidden Costs One of the most persistent challenges for individuals moving money is the opacity of exchange rates. Many traditional institutions offer an exchange rate that includes a margin or spread. This margin is essentially an added cost that the customer pays, which is often not clearly disclosed in the upfront quote. For example, a bank might quote a rate that is several percentage points lower than the actual mid-market rate, which is the midpoint between the buy and sell prices of two currencies. This hidden cost can make a substantial difference, especially when moving large sums of money. To make informed decisions, one must distinguish between the mid-market rate and the retail rate. The mid-market rate is what you see on financial news platforms or through independent search engines. Retail rates, provided by banks or service providers, often incorporate a profit margin. By comparing these rates, one can determine the true cost of a transaction. Modern financial technology has begun to shift this dynamic by offering services that utilize real-time exchange rates with lower, transparent fees. This evolution is vital for those who need to maintain purchasing power throughout the process of transferring currency across international borders. Traditional Banking versus Modern Fintech Solutions For decades, traditional high-street banks were the primary method for moving funds internationally. While these institutions offer a high degree of perceived security, they often come with significant drawbacks, including slow processing times, high transaction fees, and limited transparency regarding the specific route the money takes. Banks often rely on the SWIFT network, which involves intermediary banks to complete a transfer. Each intermediary in the chain may charge its own processing fee, further eroding the total amount of money that reaches the recipient. In contrast, specialized fintech platforms have emerged to address these inefficiencies. These platforms often use a direct-transfer model or peer-to-peer matching systems that bypass the traditional SWIFT network. By leveraging digital ledger technology and localized bank accounts in both the UK and India, these services can process transactions much faster and at a fraction of the cost. The shift from traditional banking to these specialized platforms allows for greater control over the process. Users can track their transactions in real-time, know exactly what the exchange rate is before they commit, and ensure that the funds arrive in the recipient’s bank account with minimal delay. How to Transfer Funds from England to India Effectively The process to transfer funds from England to India has become increasingly streamlined, yet it requires careful attention to detail to ensure success. The journey begins with selecting a service provider that balances speed, cost, and reliability. Once a provider is chosen, the user must create an account and verify their identity, which is a standard procedure to satisfy regulatory requirements. This step is critical; providing accurate information avoids unnecessary friction or holds on the account. After the account is verified, the user initiates the transaction by entering the recipient’s bank details, specifically the Indian Financial System Code (IFSC) and the account number. These details are precise identifiers that ensure the funds reach the correct destination. Once the transaction is initiated, the sender locks in the exchange rate. This is a crucial moment, as it dictates the final amount the recipient will receive. After the funds are sent from the UK bank account to the provider, the provider executes the currency conversion and pushes the funds into the Indian bank account via the local payment rails. This process, when done through a modernized platform, is often completed within one business day, depending on the banking hours and specific bank policies in India. Optimizing Security and Managing Large Transactions Security remains the

Uncategorized

The Complete Guide to Secure Money Transfers

Sending funds across international borders typically involves navigating a maze of hidden currency markups and correspondent banking delays. For expatriates, investors, and family members transferring British Pounds into the Ugandan Shilling, the financial infrastructure has historically relied on intermediary institutions that systematically siphon value from the principal amount. The gap between what leaves a UK account and what lands in East Africa is often obscured by poor exchange rates and unpredictable handling charges. The core issue driving these inefficiencies is not the advertised upfront fee, but rather the opaque foreign exchange margin applied during the conversion process. High-street banks and legacy operators operate on daily fixed rates that lag significantly behind real-time mid-market data. This mechanical delay in rate updating forces the sender to absorb the volatility risk, resulting in the recipient losing critical purchasing power on the ground in Kampala or upcountry districts. Solving this structural inefficiency requires abandoning legacy banking networks in favor of direct digital corridors. When you Move Money from England to Uganda using an optimized platform like DexRemit, the capital bypasses intermediary SWIFT networks entirely. By utilizing targeted liquidity pools and direct API integrations with Ugandan telecom operators, the platform ensures the exact amount dispatched mirrors the expected landing sum perfectly, stripping away the uncertainty that plagues traditional cross-border finance. Bypassing the Correspondent Banking Trap The traditional method of routing international payments relies on the correspondent banking network. A transfer initiated in London does not travel directly to a local branch in Kampala. Instead, it hops between two or three intermediary banks. Each node in this chain extracts a processing fee, known as a correspondent charge. Furthermore, if a transfer requires manual compliance checks at any of these intermediary stops, a standard transaction can stall in clearing networks for several business days. DexRemit eliminates this friction by maintaining pre-funded accounts within the destination country. Rather than pushing funds through a gauntlet of international clearinghouses, an inbound payment in the UK triggers an immediate localized release of equivalent funds directly from our secure holding accounts in Uganda. This mirroring technique isolates your money from the SWIFT network entirely. The result is a transaction that resolves locally on both ends, insulating users from the unpredictable delays and arbitrary deductions inherent to cross-border wire transfers. The Mobile Money Architecture Understanding the financial landscape of Uganda means recognizing that traditional banking is secondary to mobile financial services. The vast majority of everyday commerce, utility settlements, and rural transactions are executed via mobile money networks like MTN Mobile Money and Airtel Money. Sending a conventional wire transfer to a Ugandan brick-and-mortar bank often burdens the recipient with the logistical hurdle of traveling to a physical branch, waiting in line, and subsequently converting cash back into digital mobile funds for practical use. By integrating directly with East African telecom infrastructure, DexRemit routes funds straight into the recipient’s active mobile wallet. This technical bridge turns a complex international settlement into a localized digital handshake. The recipient receives an instant SMS notification, and the funds are immediately available for merchant payments, peer-to-peer transfers, or cash withdrawal at tens of thousands of local agent kiosks nationwide. Quantifiable Transfer Advantages Switching from legacy providers to a specialized remittance infrastructure yields immediate, measurable improvements to your baseline transfer economics. Navigating GBP to UGX Volatility The exchange corridor between the British Pound and the Ugandan Shilling is subject to distinct macroeconomic pressures, including commodity export fluctuations and regional liquidity shifts. When executing high-volume transfers for real estate purchases, business payroll, or tuition fees, a sudden 2% swing in the spot rate translates to a severe loss of capital. DexRemit provides transparent, real-time rate tracking. Unlike platforms that lock in a wider margin to protect their own bottom line against intra-day volatility, our system passes the live market efficiency directly to the sender. Before confirming the transaction, the exact payout in UGX is calculated and locked. The figure displayed on the final confirmation screen is the exact, unalterable amount that will settle in the recipient’s account, eliminating the “landing shock” common with variable-rate banking transfers. Institutional-Grade Security Protocols Operating a cross-border financial bridge requires rigorous adherence to international compliance and data protection standards. DexRemit operates under strict regulatory oversight, mirroring the security architecture utilized by major financial institutions. Every transaction is protected by end-to-end cryptographic protocols, ensuring that financial data and personal identifiers remain isolated from external interception. Furthermore, automated Anti-Money Laundering (AML) algorithms monitor transaction flows in real-time. This system proactively identifies anomalous patterns without slowing down legitimate transfers, satisfying strict UK Financial Conduct Authority (FCA) directives while maintaining the frictionless speed required by our users. Your funds are safeguarded at every stage of the journey, backed by localized compliance on the East African side to ensure smooth clearing into the local economy. Frequently Asked Questions 1. What is the fastest way to route funds to a recipient in Uganda? Direct mobile money transfers via MTN or Airtel are the fastest method. By utilizing DexRemit’s telecom integration, these transfers typically clear and become accessible to the recipient within minutes of the UK payment authorization. 2. How exactly is the exchange rate calculated? Rates are dynamically sourced from live interbank market feeds. DexRemit applies a highly competitive, transparent margin to this baseline, ensuring you secure a yield significantly better than static retail banking rates. 3. Are there limits on how much I can send in a single transaction? Yes, limits are dictated by the receiving method. Mobile money wallets in Uganda have strict regulatory caps on daily balances and incoming transaction sizes. For larger amounts, routing directly to a registered Ugandan bank account is required. 4. What happens if I input the wrong mobile money number? Our system features integrated number validation. If the telecom provider rejects the number as invalid or unregistered, the transfer is halted before funds leave the ecosystem. However, if the number is valid but belongs to the wrong person, recovering funds is highly complex. Always double-check recipient details prior to execution. 5.

Scroll to Top